Making an offer on a house is exciting, but it is also the moment when a hopeful search turns into a binding financial decision. A listing price is only one number. Your offer affects the earnest-money deposit, your cash needed at closing, the repairs you may inherit, the monthly payment you can sustain, and how much flexibility remains after you get the keys.
A budget-first offer is not a timid offer. It is a clear offer with guardrails. You know the maximum price that works with your full housing costs, the cash you can safely commit, and the conditions you need before taking on a mortgage. That clarity helps you act quickly without letting urgency write a check your future budget cannot cover.
This guide is educational, not legal or lending advice. A local real-estate agent, attorney, lender, and qualified inspector can explain the rules and contracts where you live.
Start with your all-in number, not the listing price
Before deciding what to offer, decide what owning this specific home would cost each month and each year. A mortgage payment is usually made up of principal and interest, but your budget also needs property taxes, homeowners insurance, mortgage insurance when applicable, homeowners association dues, utilities, maintenance, and a reserve for repairs. In some areas, insurance or taxes can change the affordability picture more than a small difference in the purchase price.
Use the payment shown on a lender’s Loan Estimate as a starting point once you have one, then add the costs that may not appear in the principal-and-interest figure you see in a listing. The Consumer Financial Protection Bureau (CFPB) recommends comparing official loan offers rather than relying only on an early rate quote. If you are still shopping for a lender, read our guide on how to compare Mortgage Loan Estimates before treating any payment as final.
Set two limits:
- Your payment ceiling: the monthly all-in housing cost that leaves room for saving, groceries, transportation, debt payments, and ordinary life.
- Your cash ceiling: the down payment, closing costs, earnest money, moving costs, immediate purchases, and repair reserve you can pay without draining your emergency fund.
Keep the limits private and write them down before negotiations begin. A preapproval tells a seller that a lender has reviewed information about your ability to borrow; it does not mean the maximum approval amount is comfortable for your household. The number that matters is the one that fits your own cash flow.
Separate the offer price from the cash you need to close
A buyer can be surprised by cash requirements even when the offered price fits the monthly budget. Make a simple one-page offer worksheet with these lines:
- planned down payment;
- estimated lender and third-party closing costs;
- prepaid insurance, taxes, and escrow funding where required;
- earnest money;
- inspection, appraisal, and other due-diligence costs;
- moving, essential furnishings, locks, and utility deposits; and
- a reserve that remains after closing.
Earnest money is a good-faith deposit tied to the signed purchase contract. At a successful closing it is generally credited toward your down payment or closing costs, but the contract controls what happens if the purchase does not close. Its size, who holds it, when it is due, and when it may be at risk vary by location and agreement. Do not assume that a larger deposit automatically makes financial sense. Ask your agent or attorney to explain the actual contract language and deadlines.
Closing costs are also more than a line-item nuisance. They may include lender charges, title and settlement services, government recording fees, prepaid items, and initial escrow deposits. The exact mix depends on the loan, property, and local practice. Comparing loan offers early can help you see which costs come from the lender and which are services you may be able to shop for.
Do not use every available dollar for the down payment and closing. Owning a home creates irregular expenses on its own schedule. A modest post-close reserve gives you a better chance of handling a broken appliance or urgent repair without carrying a high-interest balance. If you have been building dedicated savings buckets, our overview of sinking funds for irregular expenses can help you keep the home reserve distinct from your emergency fund.
Choose a price using three reference points
Once you know your limits, work with your agent to look at three reference points: recent comparable sales, the home’s condition and features, and the terms attached to competing offers. Comparable sales help you understand the local market, but they are not a promise of appraisal value. Condition matters because a lower-priced home that immediately needs a roof, drainage work, or major systems can be more expensive than a better-maintained alternative.
Your first number should be an offer you would be comfortable having accepted immediately. Your second number is the highest price you can accept without violating your payment or cash ceilings. Do not make the second number your opening point merely because it exists. A planned range makes it easier to respond to a counteroffer calmly.
Be especially cautious about offering more than your comfortable limit to “win” and planning to solve the gap later. If the appraisal comes in below the contract price, the lender may base the loan amount on the lower value. Depending on the agreement and loan, you may need to renegotiate, bring additional cash, or use a contractual option. This is why the financing and appraisal provisions deserve as much attention as the price.
Include the costs that arrive after moving day
A useful offer budget has a second column labeled “first 90 days.” List expenses that are easy to postpone mentally: a locksmith or rekeying, smoke and carbon-monoxide detectors, window coverings, a lawn tool or snow equipment, appliance service, pest treatment, paint, and a few utility bills that may be higher than the seller’s. You will not need every item, but planning for them keeps small purchases from turning into a credit-card balance immediately after closing.
Also look at the age and condition of systems that influence the first year of ownership. If the inspection indicates that a water heater, roof, HVAC equipment, or drainage feature is nearing the end of its useful life, put a realistic range beside it. This is not an attempt to predict every repair. It is a way to see whether the home still fits after the obvious risks are acknowledged. If the price only works when every major system performs perfectly, the price may not truly work.
For properties with homeowners association dues, ask what those dues cover, whether assessments are pending, and how the budget is funded. For condos, ask to review the relevant documents within the period allowed by your contract. For any property, get an insurance estimate early enough that it can inform your decision. A location with a higher flood, wildfire, wind, or other disaster exposure can carry costs that do not show up in a listing’s estimated payment. The CFPB suggests asking direct questions about flood and disaster risk before committing.
Understand the protections before you change them
An offer is a bundle of price and terms. The CFPB notes that financing and satisfactory-inspection contingencies can protect a buyer when financing falls through or an inspection reveals serious flaws. In a competitive market, you may hear that a buyer should waive every contingency. That is not a default budgeting tactic; it is a decision to accept more risk.
Common terms to discuss with a licensed local professional include:
- Financing contingency: addresses what happens if you cannot obtain financing under the agreed terms.
- Inspection contingency: gives you a defined period to inspect and, depending on the contract, negotiate, proceed, or cancel based on findings.
- Appraisal contingency: addresses a value shortfall and the choices available to the parties.
- Sale-of-current-home contingency: may matter if your down payment depends on selling another property.
- Title and disclosure review: helps ensure you can understand ownership, restrictions, and known property conditions.
These terms are local and contractual, so the details are not interchangeable across states. The useful question is not “Which contingency makes my offer strongest?” It is “Which risk could seriously damage my finances if it happens?” A buyer with a thin cash reserve, for example, may place a very different value on an inspection opportunity than a buyer with ample reserves and construction experience.
Budget for the inspection phase
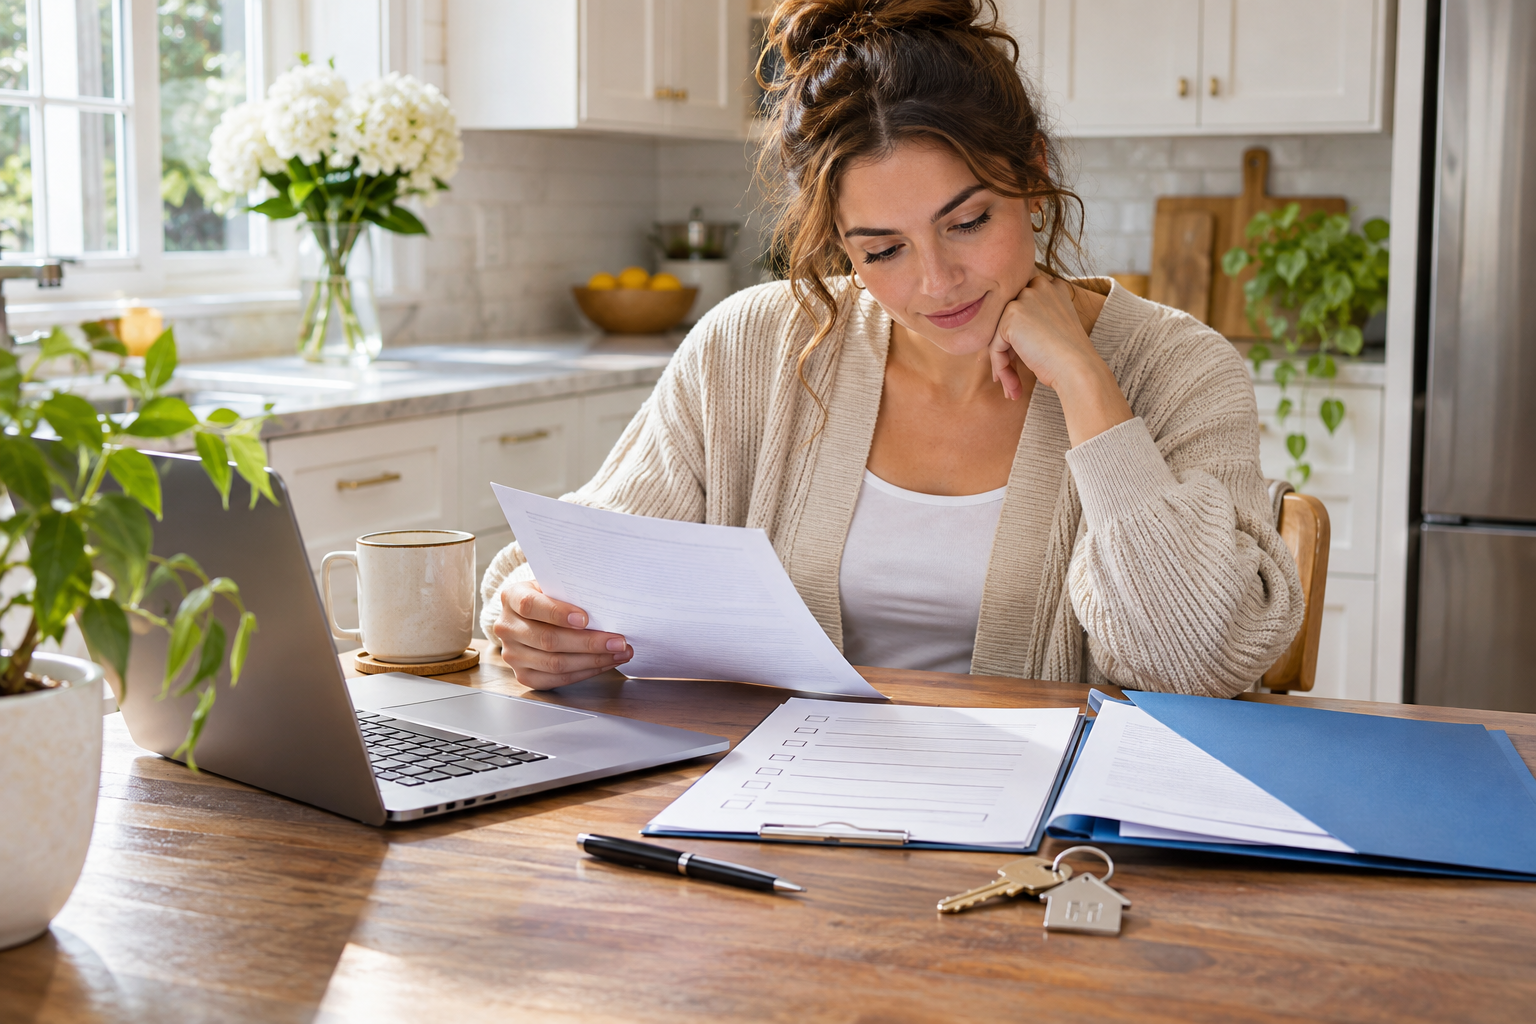
A home inspection is not the same as an appraisal. An appraisal is generally required by the lender to support the loan decision; it is not a comprehensive condition review for the buyer. The CFPB and HUD both emphasize the value of obtaining an independent inspection. Arrange it promptly after your offer is accepted, if your agreement provides an inspection period, and attend when possible. Hearing the inspector explain an issue in context is often more useful than reading a report alone.
Expect even a well-maintained house to produce a list. Sort findings into four buckets: safety or structural concerns; active water, electrical, or system failures; items nearing the end of useful life; and routine maintenance. Get qualified estimates for big-ticket issues rather than treating the report’s wording as a price quote. Then decide with your adviser whether to request repairs, seek a credit, renegotiate price, accept the condition, or walk away under the contract.
A credit can be simpler than asking a seller to manage repairs, but it does not remove the need for cash at closing and may be limited by loan rules. A price reduction can change financing math differently from a credit. Ask your lender to model the choices before agreeing to one. This is the same discipline that keeps home maintenance from becoming a surprise later; see how to budget for home maintenance for a post-close planning framework.
Protect yourself from transaction fraud
Home purchases involve large wire transfers and many emails, which makes them attractive targets for criminals. Treat any message changing wiring instructions, account numbers, or payment timing as suspicious until you verify it. Call a known phone number for your settlement agent or title company; do not use the number in a surprising email. Do not send money simply because an urgent message says a deal will collapse.
Use strong, unique passwords for email and lending portals, enable multi-factor authentication where available, and limit sensitive documents to the secure channel your lender provides. The CFPB specifically warns homebuyers to stay alert for mortgage-closing scams. A few minutes of independent verification can protect both your down payment and your offer timeline.
Plan the timeline after acceptance
Once your offer is accepted, the budget work is not over. Create a deadline calendar from your signed contract and lender requirements. Put every due date in one place: earnest-money delivery, inspection window, loan documents, appraisal, insurance selection, final walk-through, and closing. Ask which deadlines are business days and which are calendar days. Missing a date can weaken choices that were available when the offer was signed.
Keep your finances steady while the loan is in underwriting. Avoid opening new credit, financing furniture, making unexplained large deposits, changing jobs without discussing it, or moving money in ways you cannot document. The lender can request updated information before closing. If a change is unavoidable, tell the loan officer promptly rather than hoping it will not matter.
Review the Closing Disclosure carefully when you receive it. Compare it with the Loan Estimate and ask about material changes in cash to close, rate, payment, or fees. The closing process also requires homeowner’s insurance and may involve title insurance and other providers. The practical lesson is simple: reserve time, not just money, for review.
Use a calm counteroffer process
A seller counteroffer is an invitation to re-check the whole package, not just to react to the price. Recalculate the all-in payment, cash to close, inspection exposure, and timeline with every proposed change. If the seller raises the price but covers a permitted cost, ask the lender how it changes your actual cash and payment. If the seller wants a quicker closing, make sure inspections, insurance shopping, and document review can still be completed responsibly.
Give yourself a written walk-away rule. For example: “We will not exceed our maximum all-in payment, waive the inspection without an informed decision, or reduce our post-close reserve below the amount we set.” A walk-away rule makes a disappointing outcome manageable. There will be other homes; recovering from an unaffordable purchase is much harder.
A practical offer checklist
- Confirm your all-in monthly payment ceiling.
- List every cash-to-close item and your remaining reserve.
- Review comparable sales, condition, and known disclosures with your local professional.
- Set an opening offer and a non-negotiable maximum.
- Read every contingency, deadline, and earnest-money term before signing.
- Plan for inspection, appraisal, insurance, and lender requests immediately after acceptance.
- Verify payment instructions independently and safeguard your financial information.
- Re-run the budget before accepting a counteroffer or closing.
Homeownership works best when the purchase leaves room for the life you want after closing. A disciplined offer does not guarantee you will get a particular house, but it gives you something more durable: a decision you can afford to live with. For a broader first-time buyer perspective, review our guide to the hidden costs of buying a house and return to your budget before you sign.