This article is for education only and is not individualized investment, tax, legal, or insurance advice. Before choosing a retirement date, consider working with a qualified professional who can review your full situation.
A retirement date can feel like a finish line, but it is really a planning decision with several moving parts. Your age is only one of them. The stronger question is: when can your income, savings, health coverage, taxes, and daily life work together without creating unnecessary pressure?
That is why “I’ll retire at 65” is a useful starting idea, not a complete plan. Someone with a paid-off home, flexible spending, and part-time income may be able to leave work sooner. Someone else may choose to work longer—not because they have to, but because another year improves Social Security, adds savings, or makes health coverage simpler.
This guide gives you a practical framework for choosing a retirement date. It is designed to replace vague milestones with a decision you can test, update, and explain to yourself.
Start With a Retirement Window, Not One Magic Date
Pick three dates before you pick one:
- Your earliest workable date: the first point at which you could leave full-time work if you needed to.
- Your target date: the date that best fits your preferred lifestyle and financial plan.
- Your stronger-margin date: a later date that gives your plan more savings, lower debt, or easier benefits.
For example, Maya is 61. She could technically retire at 63 if she cuts travel and uses a modest part-time consulting income. Her target is 65, when she expects Medicare eligibility and two more years of contributions. Her stronger-margin date is 67, when her Social Security benefit estimate is higher and her mortgage balance is lower. None of those dates is “wrong.” The comparison reveals the trade-offs.
A range also makes retirement planning more resilient. A layoff, health issue, caregiving need, or unexpected market decline may move your real date. Planning several versions now is calmer than treating any change as a failure later.
Step 1: Build Your First-Year Retirement Budget
Your retirement account balance does not tell you whether you can retire next year. Your expected spending does. Start with a one-year budget in today’s dollars, then separate costs into three buckets.
| Bucket | What belongs here | Why it matters |
|---|---|---|
| Essential | Housing, food, utilities, insurance, taxes, basic transportation, healthcare | These costs determine your minimum income floor. |
| Flexible | Travel, gifts, dining, hobbies, home projects, new vehicles | These are the first levers if markets or expenses surprise you. |
| Irregular | Roof repairs, car replacement, dental work, family support, large deductibles | Ignoring these makes a good monthly plan look better than it is. |
Do not simply subtract commuting costs and assume everything else stays the same. Retirement can reduce some expenses while increasing others. You may drive less, but spend more on travel. You may stop contributing to a 401(k), but pay more for health coverage before Medicare. Write down the changes instead of hoping they cancel out.
Use actual bank and card history where possible. Then add a line for annual or infrequent costs by dividing them into monthly amounts. A $6,000 vehicle repair is not a monthly bill, but it is still part of a realistic long-term plan. The habit behind our guide to building an emergency fund on a tight budget applies here too: make room for real life before it becomes a crisis.
Step 2: Map Income by Date, Not Just by Source
Next, list every possible income source and the date it can begin. The timing is often more important than the label. Your list may include wages, part-time work, a pension, Social Security, rental income, a taxable brokerage account, traditional retirement accounts, Roth accounts, cash savings, or an annuity.
Create a simple timeline. In the first year after retirement, you might use part-time income and cash savings. At 65, healthcare may change. At 67, Social Security might begin. In later years, required minimum distributions may matter. A retirement plan is a sequence, not one withdrawal decision.
The Social Security Administration says retirement benefits can be claimed from age 62 through age 70, and monthly benefits increase the longer you wait to apply up to age 70. Review your personal estimates through your Social Security account rather than relying on a rule of thumb. Your health, marital situation, work plans, taxes, and need for income all matter.
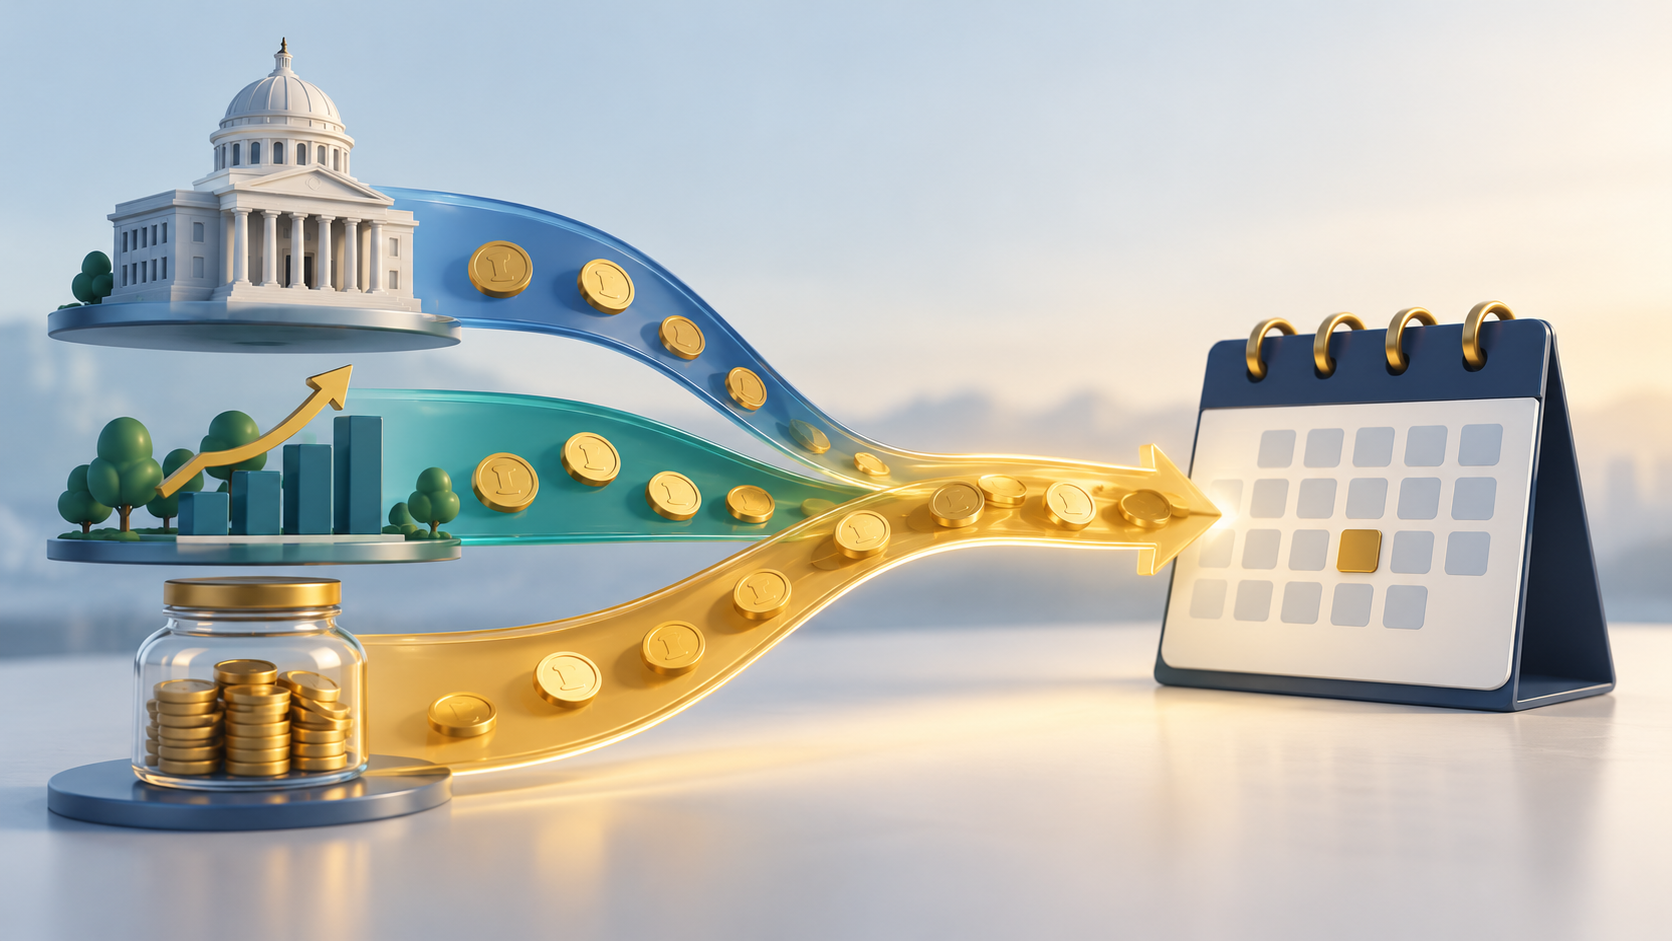
It can help to make two columns for each date you are considering: income available and spending to cover. If a gap appears, you have specific choices—work longer, spend less, save more now, claim benefits at a different time, or draw from a different account. That is much more useful than asking whether your nest egg “feels big enough.”
Step 3: Price the Healthcare Bridge
Healthcare is one of the most common reasons a retirement date changes. Medicare has its own eligibility and enrollment rules, so retiring before you are eligible may mean arranging a bridge through an employer plan, a spouse’s coverage, COBRA, a marketplace plan, retiree benefits, or another option.
Do not assume coverage is only a premium. Include deductibles, coinsurance, prescriptions, dental and vision care, and a cushion for a high-cost year. If you are married or partnered, test the dates separately. One person may be eligible for a benefit or coverage option before the other.
Medicare.gov provides plain-language explanations of coverage choices and costs. The point here is not to choose a policy from an article; it is to make health coverage a line item in every retirement-date scenario. If you retire at 63, your budget may need two years of bridge coverage. If you retire at 65, that bridge may disappear, but you still need to understand what Medicare does and does not cover.
Step 4: Test Your Plan Against a Bad First Two Years
A plan that works only if investment returns are strong is not a comfortable plan. Instead, run a rough stress test: What would happen if your first two retired years included a market decline, a major home repair, or less part-time work than expected?
You are not trying to forecast the future. You are looking for flexibility. A practical stress test asks:
- How many months of essential spending can cash cover?
- Which flexible expenses could be delayed?
- Would you be forced to sell investments after a decline?
- Could one spouse return to part-time work if needed?
- Could you reduce withdrawals for a year without losing the plan?
A written investment policy statement can help keep investment decisions separate from the emotion of a bad market. It will not eliminate risk, but it can clarify what you intend to do before volatility shows up.
Step 5: Account for Taxes Before You Need the Money
Retirement income is not one tax category. A withdrawal from a traditional 401(k) or IRA is generally different from a qualified Roth withdrawal or a sale in a taxable brokerage account. Social Security, pension income, interest, dividends, and capital gains can interact in ways that affect your tax bill.
You do not need to build a full tax projection alone to choose a target date. But you should know where your money sits and which years may create unusual income. A person retiring at 62 and delaying Social Security could have a lower-income window; a person who works until 70 could have several years of wages plus required withdrawals later. Both situations deserve a deliberate tax conversation.
The IRS notes that required minimum distributions generally begin at age 73 for many traditional retirement accounts, while Roth IRAs do not require lifetime distributions for the original owner. Those rules are detailed and can change, so use current IRS guidance and a tax professional for decisions. The key retirement-date lesson is simple: your future withdrawals should be planned by account type, not pulled at random.
For a foundation on future income sources, see our guide to building a personal retirement paycheck. If Roth accounts are part of your plan, our article on maximizing a Roth IRA explains why tax diversification can be valuable.
Step 6: Decide What Work Means in Your Transition
Retirement does not have to be a binary switch. A phased retirement can mean fewer hours, contract work, seasonal work, consulting, or simply a plan to work one more year with a clearly defined savings goal. The value is not only the paycheck. Continuing to work may preserve health coverage, delay withdrawals, increase benefits, and give you time to test your preferred routine.
Be careful, though, not to assume part-time income will appear automatically. Treat it as a separate plan: What kind of work is realistic? How many hours are sustainable? Does it affect benefit timing? What happens if it ends early? Use conservative numbers in the budget.
Before you leave a role, also understand what you would be giving up: a match, pension accrual, stock compensation, paid health coverage, life insurance, disability insurance, or access to a group plan. Sometimes the final working year is financially meaningful; other times it is less valuable than your well-being and time. The answer is personal, but the comparison should be explicit.
Step 7: Check Debt, Housing, and Family Commitments
Housing is often the largest fixed item in a retirement budget. You do not necessarily need a paid-off mortgage to retire, but you do need a clear payment, payoff timeline, maintenance reserve, and plan for property taxes and insurance. Compare your desired retirement date with your mortgage payoff date rather than treating them as unrelated events.
Also list loans, credit cards, car payments, and family commitments. A plan can be workable with debt, but high-interest balances and inflexible monthly payments reduce your margin for error. If you are debating homeownership changes, our guide to the hidden costs of owning a home is a useful reminder that the purchase price is never the whole housing budget.
Finally, have an honest family conversation. Caregiving, adult children, a partner’s career, and the desire to live near grandchildren can all change both spending and timing. These are not side notes; they are inputs to the decision.
A Simple Retirement-Date Scorecard
For each candidate date, score the following as green, yellow, or red:
- Monthly essentials: Are they covered by reliable income plus a sustainable draw plan?
- Healthcare: Is coverage and out-of-pocket exposure understood?
- Cash reserve: Can you handle a surprise without selling long-term investments immediately?
- Debt: Are payments manageable if income drops?
- Taxes: Do you know which accounts will fund the first several years?
- Investment risk: Does your allocation match the reality of upcoming withdrawals?
- Plan B: Do you know what you would change if expenses rise or returns disappoint?
- Life fit: Does the date support the work, home, health, and relationships you want?
Several yellow items may be manageable if you have a clear action plan. A red healthcare gap or a red essential-spending gap deserves more work before you give notice. This scorecard does not replace professional advice; it helps you arrive at that conversation organized.
Common Mistakes When Picking a Retirement Date
Choosing based on age alone
Age can determine eligibility, but it cannot tell you whether your cash flow is ready. Use dates as prompts to investigate benefits, not as automatic answers.
Using one average monthly number
Annual bills and irregular expenses can quietly break a tidy monthly estimate. Include them before you decide a plan is affordable.
Ignoring the gap before benefits start
Many plans look solid in later retirement but are strained in the first few years. Map each source by start date.
Assuming a home is “free” once the mortgage is gone
Taxes, insurance, utilities, maintenance, and accessibility updates still require cash.
Treating a retirement date as irreversible
You can revisit the date each year. Better information, changing priorities, and market conditions may justify a different choice.
FAQ: Choosing a Retirement Date
How do I know if I can retire this year?
Start with a first-year budget, map income by date, price healthcare, and test a bad-market scenario. If essential spending has a persistent gap, identify the change that closes it before you retire.
Should I wait until 65 to retire?
Age 65 may simplify health coverage for many people, but it is not automatically the best date. Compare it with earlier and later dates using your actual spending, benefits, work options, and savings.
Can I retire before claiming Social Security?
Yes, some people use savings, work income, or other resources before claiming. Whether that is wise depends on cash flow, taxes, longevity, spouse benefits, and personal goals. Review your Social Security estimates before deciding.
What if I am not ready by my target date?
Move from a fixed deadline to a specific adjustment: increase savings, reduce a recurring cost, pay off a debt, work part-time, reconsider housing, or delay the date. A changed date is information, not defeat.
Final Takeaway
The best retirement date is not the earliest possible one or the date someone else chose. It is the date when your spending, income timing, healthcare, tax picture, investment plan, and personal life can work together with enough flexibility for surprises.
Choose a retirement window, test the numbers, identify the weak spots, and revisit the plan regularly. That turns retirement from a leap of faith into a decision you can make with open eyes.