How to Build a Retirement Budget Before You Retire
Retirement budgeting is not about guessing what every future grocery trip will cost. It is about building a monthly spending plan that works when the paycheck stops, then pressure-testing it before the decision becomes permanent.
That sounds simple, but the transition from working to retired can change almost every line of a budget. Commuting and payroll deductions may disappear. Health insurance, travel, home repairs, taxes, and help for family may become more visible. Income may arrive from several places on different schedules. A good retirement budget turns all of that into one clear question: will my dependable income, savings withdrawals, and cash cushion support the life I want?
This guide shows you how to build that budget in a way you can actually use. It is educational, not personalized financial, investment, or tax advice. For decisions involving a pension election, Social Security claiming, withdrawals, or tax planning, consider reviewing your plan with a qualified professional.
Start with a retirement budget, not a percentage rule
A rule of thumb can be a useful conversation starter, but it cannot tell you whether your own retirement plan works. Two households with the same pre-retirement income can need very different amounts: one may have a paid-off home and a pension; the other may rent, support an adult child, or face a large gap before Medicare eligibility.
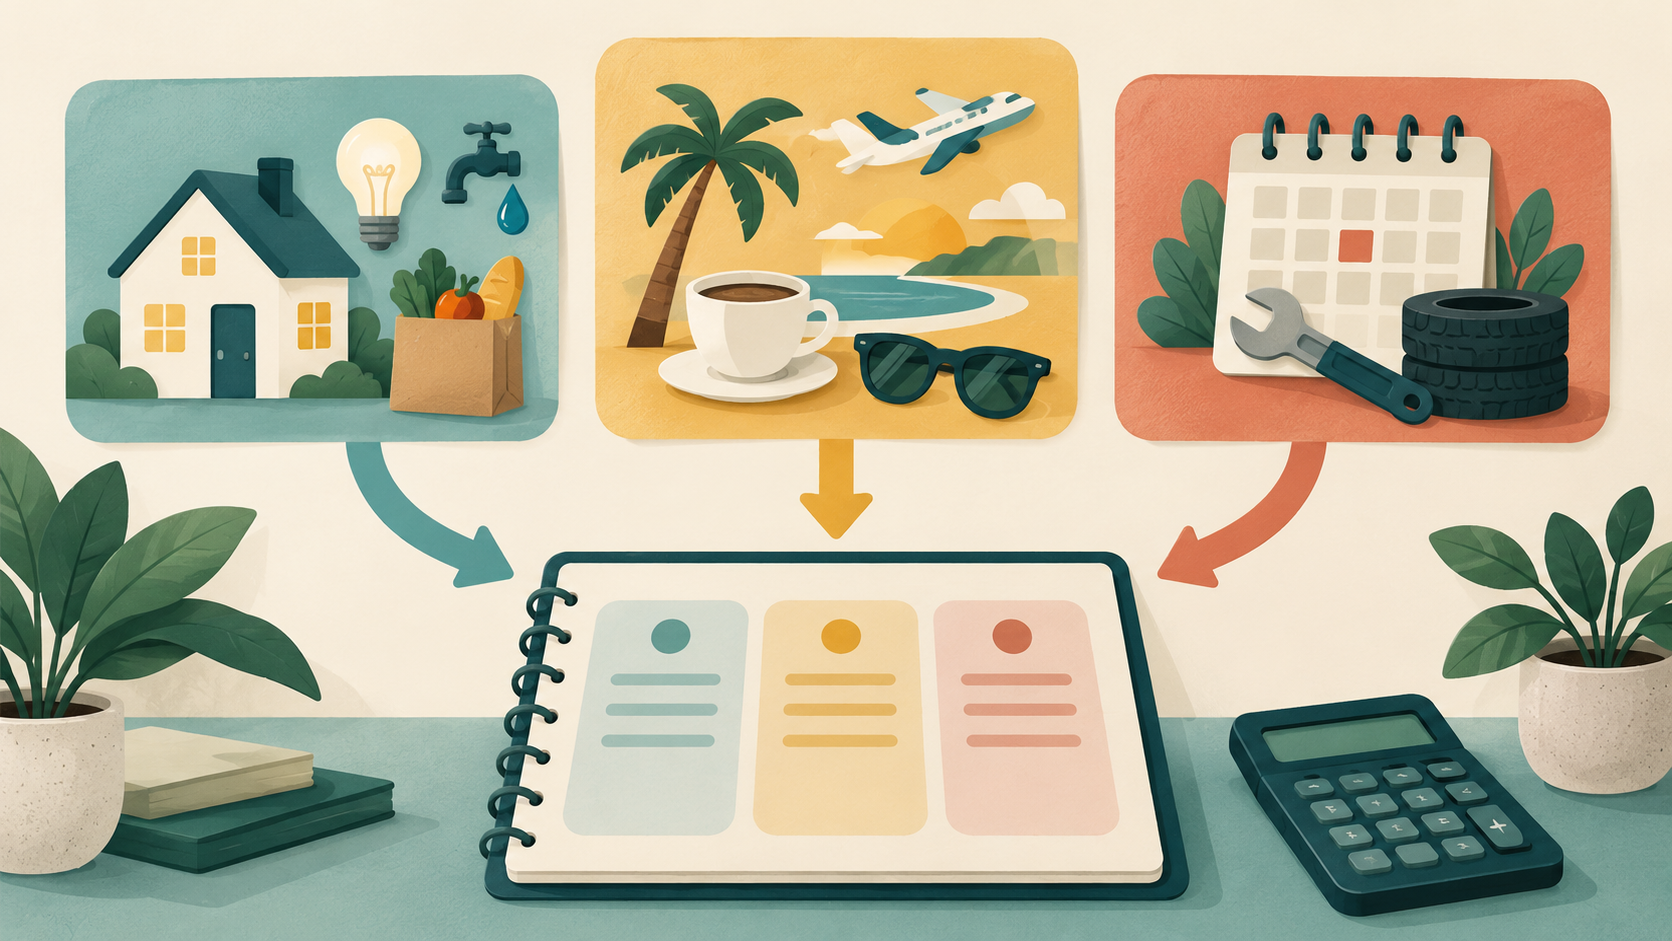
Build your first version from your real spending. Pull the last 6 to 12 months of checking-account, credit-card, and bill-payment activity. Then sort every expense into one of three buckets:
- Core needs: housing, utilities, food, insurance, transportation, health care, debt payments, and basic household costs.
- Flexible wants: travel, gifts, dining out, hobbies, subscriptions, and upgrades.
- Irregular costs: property taxes, insurance premiums, car replacement, home repairs, dental work, holidays, and family support.
The third bucket is where many retirement budgets break down. An expense that appears once or twice a year is still part of your lifestyle. Convert it into a monthly amount by dividing the expected annual cost by 12, then move that amount into a dedicated savings bucket. The same sinking-fund approach described in our guide to sinking funds for irregular expenses works especially well when income becomes less predictable.
Separate the budget into four useful layers
A single monthly total is helpful, but four layers make it far easier to make decisions. Think of them as versions of the same budget rather than four unrelated plans.
| Layer | What it includes | Why it matters |
|---|---|---|
| Essential floor | Housing, food, insurance, basic transportation, minimum debt payments, and essential care | Shows the income you must protect first. |
| Normal lifestyle | Your usual discretionary spending plus realistic recurring costs | Shows what your preferred retirement looks like. |
| Active years | Travel, experiences, hobbies, and extra family spending | Prevents you from assuming all spending falls immediately after work ends. |
| Contingency plan | Reduced flexible spending and delayed large purchases | Gives you an adjustment plan for a bad market, a repair, or a surprise. |
For example, a household may find its essential floor is $4,200 per month, its normal lifestyle is $5,400, and its active-years plan is $6,200. That does not mean $6,200 is wrong. It means the couple can see exactly which choices are optional if circumstances change. Clarity is more useful than false precision.
Replace your paycheck with named income sources
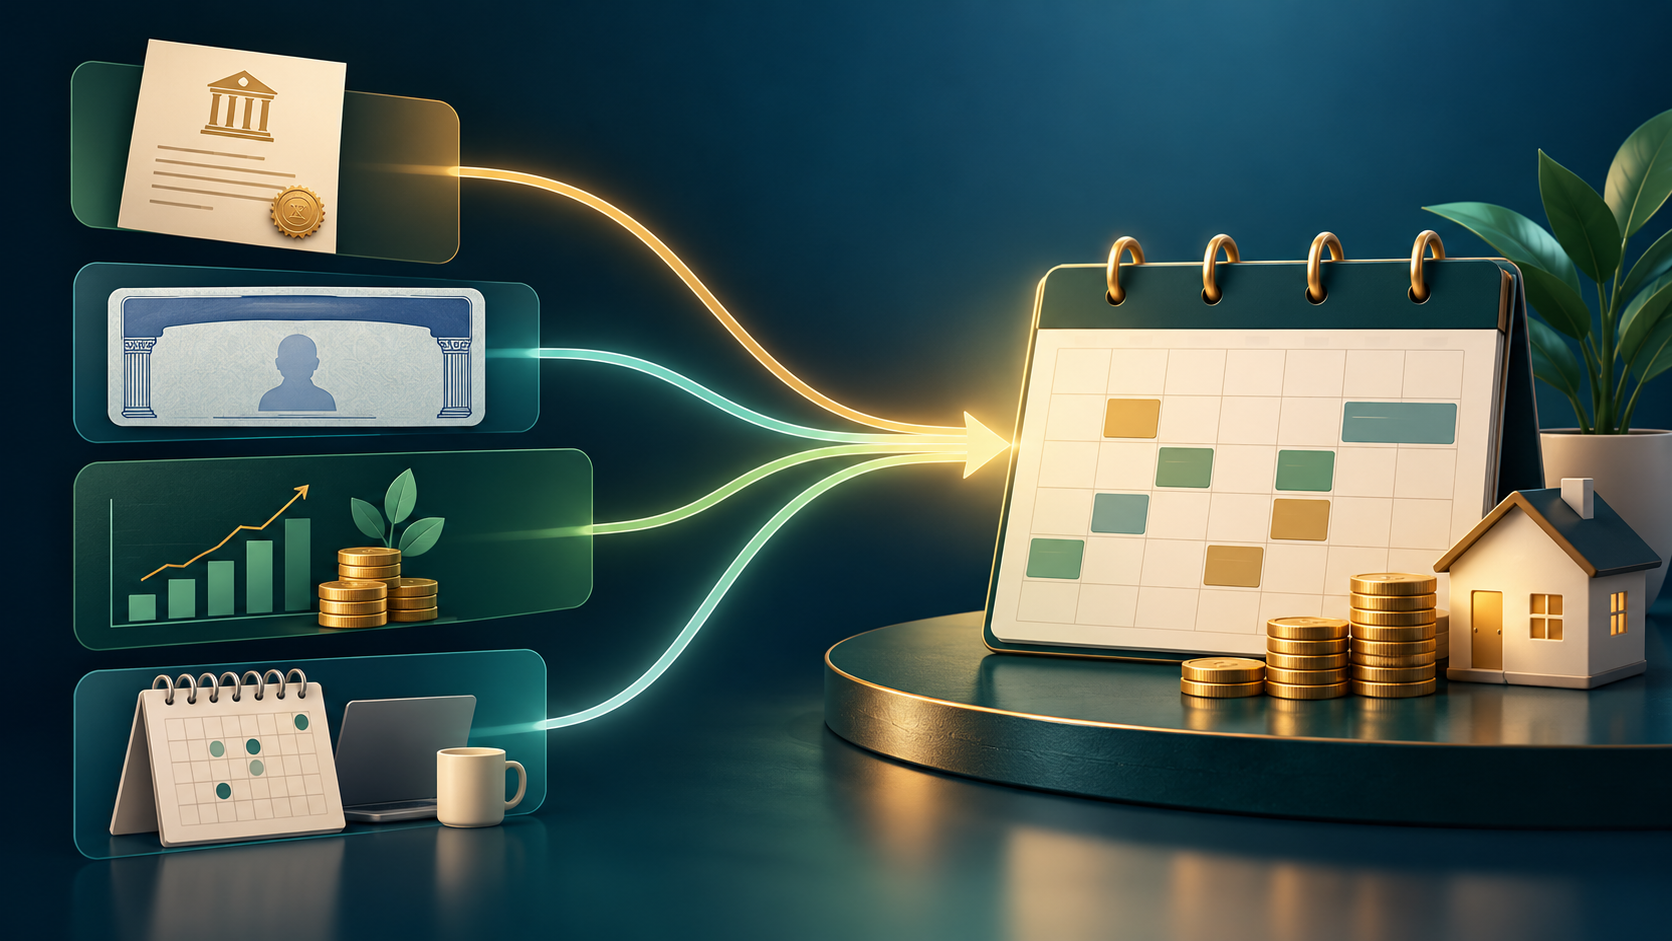
Next, make an income calendar. List each source, when it begins, whether it is guaranteed or market-dependent, whether it is before or after tax, and how often it is paid. Common sources include Social Security, pensions, part-time work, annuity payments, rental income, interest, dividends, and withdrawals from retirement accounts.
Do not treat every dollar as equally dependable. A pension payment and a planned portfolio withdrawal may both help pay the bills, but they behave differently. Labeling them makes the plan more honest.
Use a simple order:
- Match dependable income against the essential floor.
- Use flexible income and planned withdrawals for the rest of the normal lifestyle.
- Fund travel and big discretionary goals only after the first two layers are covered.
Get an official estimate rather than relying on an old statement or memory. The Social Security Administration’s retirement planning tools can help you review estimated benefits and the effect of different claiming ages. If you are weighing the date itself, pair this budget work with our retirement-date decision framework.
Here is a simplified illustration. Suppose Jordan’s essential floor is $4,200 a month. A pension and Social Security are expected to provide $3,100 after estimated withholding. The remaining $1,100 is the monthly gap to plan for before adding travel or gifts. That gap may come from part-time income, a planned account withdrawal, a later claiming date, lower fixed costs, or some combination. The point is not to pick an answer from a blog; it is to show the gap in plain view.
Map the first two years, not just the first month
The handoff from work income to retirement income is rarely perfectly smooth. Your final paycheck, unused leave payout, bonus, severance, pension start date, Social Security start date, health coverage, and retirement-account withdrawal schedule may all land in different months. A budget that looks fine in year two can still be strained in the first few months if you have not planned the bridge.
Create a simple 24-month calendar with one row for income and another for large expenses. Mark the month each income source begins, when employer coverage ends, when a premium changes, and when you expect annual insurance or property-tax bills. Include a reasonable amount for tax withholding instead of assuming the gross deposit is available to spend.
This exercise often reveals an easy fix. You might keep a little more cash before retiring, change the month a benefit begins, schedule a planned withdrawal rather than taking an ad hoc one, or delay a nonessential purchase. It can also expose a genuine mismatch early enough to reconsider a retirement date or discuss options with a planner.
If one spouse retires first, build a version for that transition too. The household may have one salary for a while, but its insurance, taxes, and contributions can change. A phased-retirement budget is more realistic than treating retirement as a single on/off switch.
Budget for health care before and after Medicare
Health care deserves its own section because it can change sharply around retirement. If you stop working before you qualify for Medicare, estimate the full cost of replacing employer coverage, including premiums, deductibles, prescriptions, dental care, vision care, and out-of-pocket limits. Do not assume the amount deducted from your final paycheck represents the full cost of coverage.
After Medicare begins, keep budgeting. Medicare choices, supplemental coverage, prescription coverage, and services not fully covered can all affect household cash flow. Start with the official Medicare costs overview, then compare your expected coverage and local options during the appropriate enrollment window. This is also a good time to update beneficiaries and account records.
Use two health-care lines in your budget:
- Recurring monthly care: premiums, prescriptions, routine appointments, and medical supplies.
- Reserve for irregular care: dental work, hearing or vision expenses, uncovered services, travel to care, and a higher-than-usual deductible year.
That reserve is not a prediction that something bad will happen. It is a way to avoid treating a known possibility as an emergency. The same distinction matters when you decide how much emergency savings to hold before retirement.
Put taxes into the monthly plan
Retirement income can be taxed differently depending on its source. Traditional retirement-account withdrawals, pension income, investment income, and part of Social Security benefits can affect your tax picture. Qualified Roth distributions follow different rules. Your state may have its own treatment as well.
The practical lesson is straightforward: use after-tax income in your spending plan whenever possible. If a pension quote is stated before withholding, do not budget the gross payment as spendable cash. The IRS notes that retirees may need to revisit withholding or make estimated payments as their income changes; its retirement tax guidance is a sensible starting point. You can also use the tax-document checklist to organize the records that make annual review easier.
Make a short tax checklist for your first retirement year:
- Confirm withholding elections on pension, annuity, and retirement-account payments.
- Estimate whether any Social Security benefits may be taxable based on your overall income.
- Ask how required minimum distributions could affect future cash flow if they apply to you.
- Set a calendar reminder to review withholding after the first few payments arrive.
This is not the moment to optimize every last dollar. First, avoid budgeting money you will owe in tax later.
Plan for the costs that do not arrive monthly
Homeowners should keep a maintenance and replacement line even if the mortgage is gone. A paid-off home still needs insurance, property taxes, appliances, roofing, plumbing, and seasonal work. Create a written list of major systems, their approximate ages, and the next likely expense. This home-maintenance budgeting guide can help you turn vague worry into a monthly target.
Do the same for vehicles, gifts, travel, pets, professional services, and helping family. If you expect to replace a car in five years, add a monthly contribution now instead of treating the eventual purchase as a crisis. A retirement budget should reflect the life you intend to live, not just the bills that happened to arrive last month.
Build a cash buffer for timing and surprises
A retirement plan can be sound on an annual basis and still feel stressful if the timing is awkward. A tax bill, home repair, or market decline can arrive when you prefer not to sell investments. A cash buffer gives you more choice about when to withdraw and when to wait.
There is no universal cash number. Start by identifying the amount needed to cover your essential floor for a period that makes you comfortable, then add known near-term expenses. Keep the goal separate from investment strategy: the purpose is liquidity and stability, not maximizing returns. If you are new to thinking in terms of account roles, our beginner investing guide explains why goals, time horizon, and diversification come before product selection.
Test the budget before your last day of work
The most valuable retirement budget is tested while you still have options. Try a 90-day practice run. Transfer the difference between your current take-home pay and planned retirement income to savings, and live on the retirement budget where practical. You will quickly see which categories were too optimistic and which work expenses genuinely disappear.
Then run three scenarios:
- Base case: normal lifestyle spending and the expected start dates for income.
- Higher-cost case: add a repair, higher medical cost, or travel to help family.
- Lower-income case: postpone a discretionary goal, reduce flexible spending, or test a temporary drop in portfolio withdrawals.
You are not trying to forecast every setback. You are identifying the first two or three adjustments you would make. That is a much more useful plan than a spreadsheet that only works in perfect conditions.
A one-page retirement budget template
Use this outline for your first draft. Round numbers are fine at first; refine them after you test the plan.
- Essential monthly spending: $______
- Normal monthly spending: $______
- Monthly irregular-expense funding: $______
- Expected after-tax dependable income: $______
- Planned withdrawals or flexible income: $______
- Monthly gap or surplus: $______
- Cash reserve target: $______
- First adjustment if income falls or costs rise: ______
Review the plan at least annually and after major changes such as a move, a spouse’s retirement, a new health condition, a pension election, or a change in work income. Retirement is not one decision; it is a series of decisions supported by a living cash-flow plan.
Frequently asked questions
How much of my pre-retirement income will I need?
A percentage can be a rough starting point, but it is not a budget. Build your own estimate from expenses, health coverage, taxes, debt, travel, and irregular costs. The result may be higher or lower than a common rule of thumb.
Should I include Social Security in my retirement budget?
Yes, if you use a current estimate and document when you expect payments to begin. Keep the amount separate from other income sources and use an after-tax estimate when you can.
What if my retirement budget shows a gap?
A gap is useful information, not a failure. Explore the levers available to you: a later retirement date, delayed benefits, lower fixed costs, a smaller spending target, part-time income, a different withdrawal plan, or more saving before retirement. The right choice depends on your full situation.
The bottom line
A retirement budget gives your retirement date a real-world test. Start with actual spending, include irregular costs, map each income source, use after-tax numbers, and create a cash buffer. Then test the plan before you need to rely on it. A budget cannot remove uncertainty, but it can tell you what matters, what is flexible, and what action you would take next.